 English
 العربية
Refund of Value Added Tax on Real Estate Sales by Individuals, Pursuant to Zakat, Tax and Customs Authority Board Resolution No. (26-04-10), Dated 3/3/1448 AH
Introduction
If you sold a plot of land or a house in your personal capacity between 1 January 2018 and 4 October 2020 and paid Value Added Tax (VAT) on that sale, you now have a legal avenue to recover the amount paid. In October 2026, the General Secretariat of the Zakat, Tax and Customs Committees opened the filing of refund claims pursuant to Royal Order No. (54152), dated 5/7/1447 AH.
This article is not merely a restatement of the official announcement. It is a practical guide for anyone seeking answers to three questions: Am I eligible? How much can I recover? And what could cause my claim to fail despite my entitlement?
When Does the Deadline Begin?
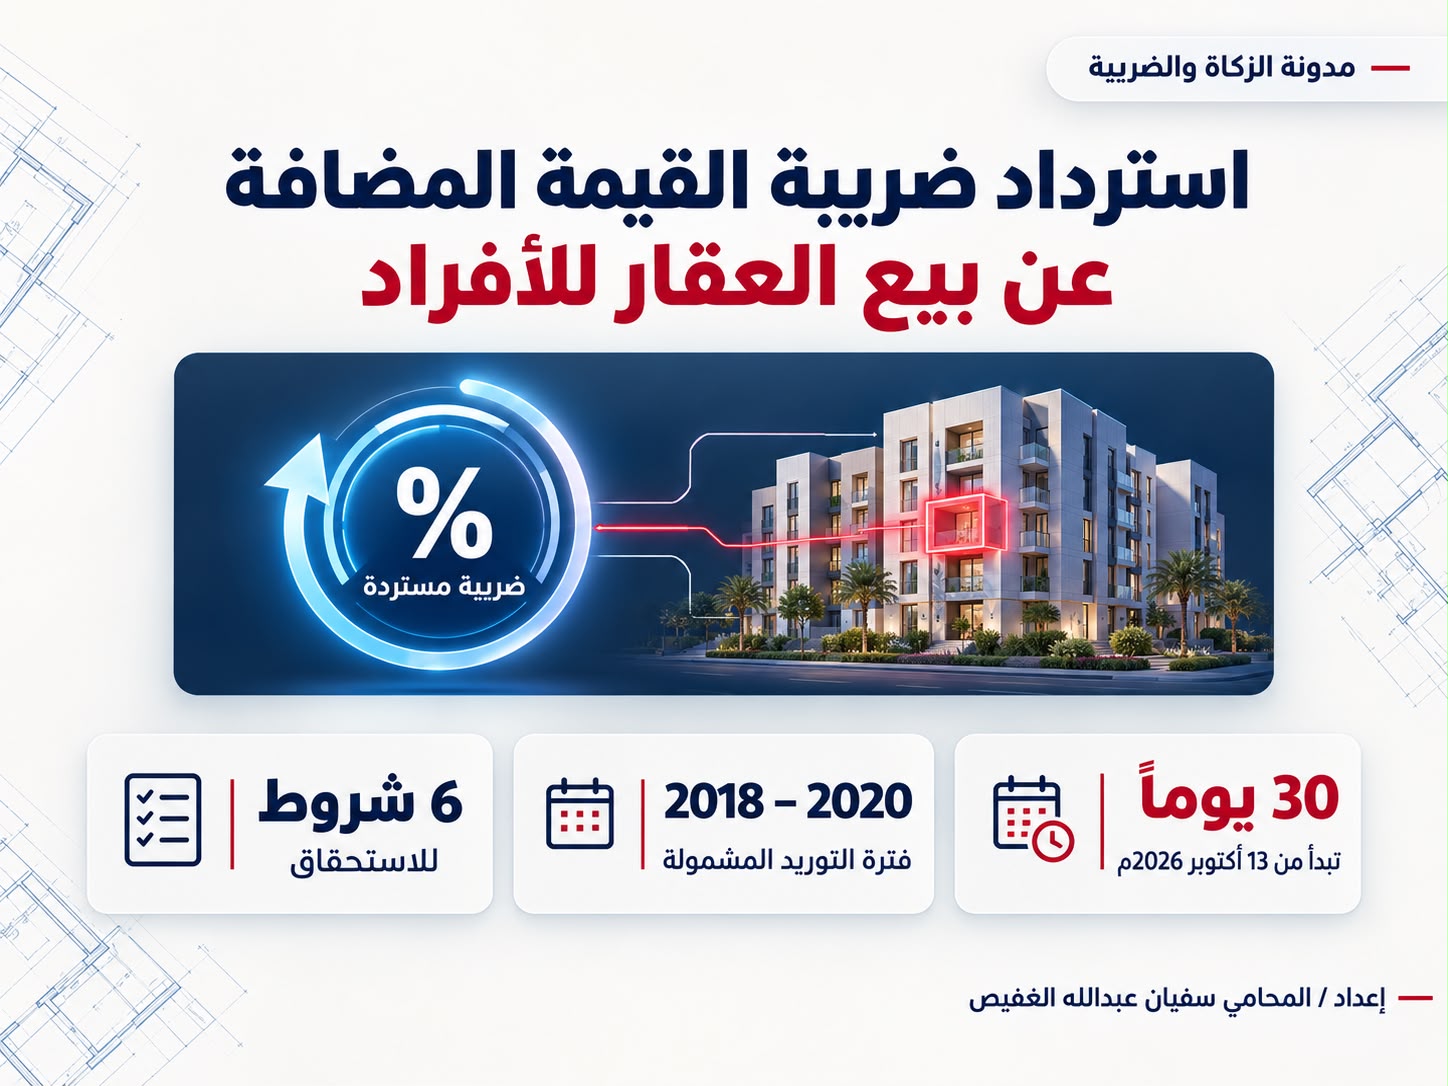
The thirty-day period begins on the date the mechanisms and procedures are published in the Official Gazette (Umm Al-Qura), which was 13 October 2026, corresponding to 2/5/1448 AH. The final day for filing claims is Wednesday, 11 November 2026, according to the guidance issued by the General Secretariat of the Committees.
Filing the claim within this period is a condition of eligibility, not merely a procedural formality. A claim filed after the deadline is liable to be declared inadmissible. Accordingly, filing should not be postponed until the final days.
How Did the Issue Arise?
When VAT was introduced at the beginning of 2018, real estate sales became subject to the tax. The distinction between a person engaged in real estate activities as a regular and continuous business and an individual selling inherited land or a home in which they had lived was not always clear. As a result, many individuals found themselves required to register, submit tax returns, and pay tax—and sometimes late-payment penalties—for a transaction that might have been the only real estate sale of their lives.
This situation came to an end on 4 October 2020, when real estate supplies were exempted from VAT and replaced by Real Estate Transaction Tax at a rate of 5%. However, amounts paid before that date remained unresolved until Royal Order No. (54152) was issued.
The essence of the Royal Order is that it retrospectively redefines who is liable for the tax. An individual who does not carry on real estate activity on a continuous and regular basis for the purpose of generating income was not liable for VAT in the first place. Any tax paid by such an individual may be recovered through a claim before the Committees, in accordance with the mechanisms approved by the Board of the Zakat, Tax and Customs Authority under Resolution No. (26-04-10), dated 3/3/1448 AH, corresponding to 16 August 2026.
Who Is Eligible for a Refund?
The General Secretariat’s guidance identifies six eligibility requirements. Failure to satisfy any one of them may result in the claim being rejected:
1. The claimant must be an individual. The claimant must be a natural person who remitted the tax to the Authority. Companies and establishments are not covered by this mechanism.
2. The supply must fall within the refund period. The relevant period runs from 1 January 2018 to 4 October 2020. For this purpose, a real estate supply means a transaction involving a sale and transfer of ownership; leases are not included.
3. The individual must not have made more than one real estate supply within any consecutive twelve-month period with a combined value exceeding the mandatory registration threshold. This is the practical criterion used to determine whether the individual was not carrying on real estate activity on a continuous and regular basis, as stated in the Royal Order.
4. The individual must not have deducted input tax relating to the property that is the subject of the claim.
5. The individual must not have recovered the tax amount claimed from any government entity. This condition is likely to arise in transactions where the State bore the tax on behalf of the purchaser under the First Home programme.
6. The claim must be filed within the prescribed period. This means within thirty days of publication of the mechanisms, with 11 November 2026 being the final filing date.
The individual must also have actually paid the tax to the Authority. If the tax has not been paid, the Authority will cancel the incorrectly imposed tax and its penalties by amending the relevant return or assessment, without the need to file a claim.
Practical rule: An individual who sold one property, or sold more than one property provided that the combined value of the sales in any consecutive twelve-month period did not exceed the mandatory registration threshold, will generally qualify, provided that the claim is filed within the prescribed period.
Who Is Not Eligible?
Four circumstances may exclude an individual from obtaining a refund, even if they were not professionally engaged in real estate activity.
First: Multiple sales exceeding the registration threshold. If an individual completed more than one sale within a consecutive twelve-month period and the combined value exceeded the mandatory registration threshold, the tax was payable. The threshold was not the same throughout the entire period. According to the guidance, it was SAR 1 million from 1 January 2018 to 19 December 2018, and was subsequently reduced to SAR 375,000 from 20 December 2018 onwards. The twelve-month period is calculated from the date of the first real estate supply, rather than by reference to the calendar year. A single sale, regardless of its value, does not fall within this exclusion because the rule requires more than one transaction.
Second: Deduction of input tax. This is the most significant and least frequently noticed condition. If an individual deducted, in their tax return, input tax paid in relation to the same property—for example, tax paid on its purchase or on construction contracting services—they effectively treated themselves as a taxable business. In that case, they lose the right to recover the tax and may only benefit from the cancellation of penalties that remain unpaid.
Third: The supply falls outside the refund period. The relevant date is the date of the supply, not the date of payment. An individual who sold a property in September 2020 and paid the tax in 2021 falls within the relevant period. An individual who transferred ownership after 4 October 2020 does not.
Fourth: Expiry of the filing deadline. Anyone who fails to file the claim by 11 November 2026 will have failed to satisfy one of the eligibility requirements.
The Authority may subsequently verify compliance with the requirements. If it later determines that an individual received a refund without entitlement, it may demand repayment of the amount together with the applicable penalties. A claim based on inaccurate information may therefore result in a counterclaim against the claimant.
What About Penalties?
The general rule established by the guidance is that penalties follow the tax. Where the tax is eligible for a refund, the associated penalties are also eligible for recovery.
| Individual's status | Penalties already paid | Unpaid penalties |
|---|---|---|
| Tax was not legally payable by the individual | Recovered through the same claim as the tax | Cancelled by the Authority |
| Tax was legally payable by the individual, such as where multiple sales exceeded the threshold or input tax was deducted | Not recoverable | Cancelled after payment of the principal tax |
The only exception is penalties imposed for tax evasion, which remain payable in all circumstances.
The practical consequence is clear: anyone who paid the tax late and also paid a late-payment penalty should claim both amounts. Claiming only the principal tax may result in the loss of part of their entitlement.
Five Mistakes That Weaken an Otherwise Valid Claim
Based on the files we encounter, the problem is usually not eligibility itself, but inconsistencies between figures and dates.
1. Attaching the wrong title deed. Some claimants attach the deed establishing their ownership of the property instead of the deed evidencing its sale. The deed that proves the supply is the sale deed.
2. Inconsistency between the tax and the sale price. Before filing, divide the tax paid by the applicable tax rate. The result should equal the sale price stated in the deed. Any discrepancy is likely to prompt questions from the Authority.
3. Confusing the 5% and 15% rates. The VAT rate increased to 15% effective 1 July 2020. Accordingly, the general rule is that sales before that date were subject to 5%, while sales after that date and up to 4 October 2020 were subject to 15%, subject to the transitional rules for contracts concluded before 11 May 2020. This difference alone may reveal that the invoice does not relate to the attached deed.
4. Claiming the entire amount declared in the tax return. If the return includes supplies other than the property in question, only the portion attributable to that property may be recovered. An excessive claim undermines the credibility of the remainder of the application.
5. Overlooking the anticipated argument that the ownership period was short. Someone who purchased and resold a property within a few months at an apparent profit may face an argument that they were trading in real estate. The direct response is that the guidance establishes the number and value of supplies within twelve months as the eligibility criterion, rather than the profit made on an individual transaction. The claimant should address this argument in their supporting submissions from the outset rather than waiting for the Authority to raise it.
Frequently Asked Questions
Is it necessary to submit an objection or grievance to the Authority before filing a claim?
No. The claim is filed directly with the General Secretariat of the Committees through the Hiyad portal, without a prior objection or grievance to the Authority.
Which claim category should I select on the portal?
The claim category is “Value Added Tax,” and the claim type is “Refund of Value Added Tax on Real Estate Supplies by an Individual.” This is a dedicated claim type that the guidance distinguishes from the ordinary claim category.
I sold a single plot of land for more than SAR 1 million. Does exceeding the registration threshold disqualify me?
No. The exclusion requires more than one supply within twelve months. A single sale does not fall within this exclusion, regardless of its value.
The purchaser paid the tax on top of the sale price. Who should file the claim?
The right to file belongs to the individual who remitted the tax to the Authority, namely the seller. The relationship between the seller and purchaser following the refund is governed by their contract, an issue that the mechanisms do not expressly address.
Can an authorised representative or lawyer file the claim?
Yes. A representative may be authorised to file the claim and conduct proceedings before the Committees in accordance with the Law of Advocacy, provided that the power of attorney is attached and, where the representative is a lawyer, their practising licence is also provided.
The property owner has died. Can the heirs submit a claim?
The mechanisms and guidance do not address this situation. As a general principle, financial rights pass to the heirs. However, the prudent course is to verify the filing procedure and required documents with the General Secretariat, including the certificate identifying the heirs and the relevant power of attorney.
The decision was issued in my favour. How do I receive the refund?
A final decision ordering a refund is implemented by submitting a refund request through the electronic portal of the Zakat, Tax and Customs Authority.
Can VAT on commercial leases be refunded?
No. The scope is limited to supplies involving a sale and transfer of ownership.
Conclusion
Royal Order No. (54152) does not grant a new benefit; rather, it retrospectively corrects a previous situation. A successful claim requires a consistent file in which the title deed corresponds to the tax return, the return corresponds to the invoice, and the invoice corresponds to the payment, with no discrepancies in figures or dates. The claim must also be filed before 11 November 2026.
Al-Mohaimeed Law Firm and Legal Consultancy provides services to review your file before filing, verify compliance with the eligibility requirements, prepare the statement of claim, and follow up on proceedings before the Zakat, Tax and Customs Committees. Contact us to have your documents reviewed.
This article is intended for general awareness and does not replace an assessment of each case on its own merits.
Prepared by: Lawyer Sufyan Abdullah Alghafis
Add New Comment